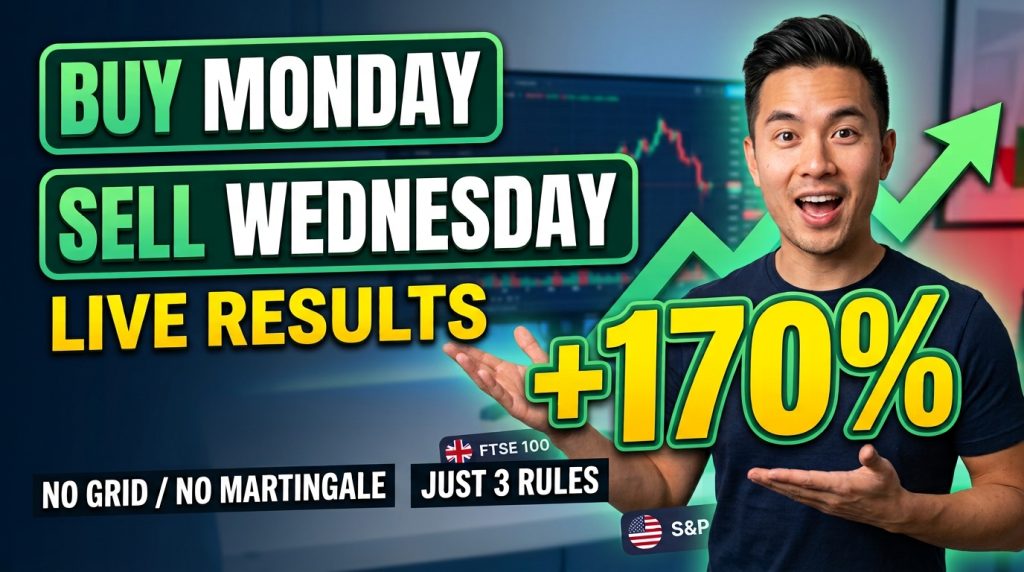
Buy Monday, Sell Wednesday. Three Rules, No Grid, No Martingale.
MonDip DailyLong is built on three rules. The entry is evaluated on the Monday daily bar once it has closed: if Monday close is below the previous trading day close, which is normally Friday, it opens a long position at market. If Monday close is equal to or above that reference close, the week is skipped entirely. The exit closes the position when the Wednesday daily bar closes, win or lose, so the holding period is under two days and no position is ever held over a weekend. The stop loss is set as a percentage of the entry price, 10% in the example, attached at entry and respecting the symbol minimum stop distance. Two optional filters exist and both can only make entry stricter, never looser: IBS, which is the close position inside the day range where a lower reading means the close sits nearer the day low, and a 180-day simple moving average filter requiring price to be below the long-term line. The EA runs on whatever symbol the chart carries, so it can be attached to FTSE 100, UK100, S&P 500 or US500 index CFDs, and decisions use daily bars only.
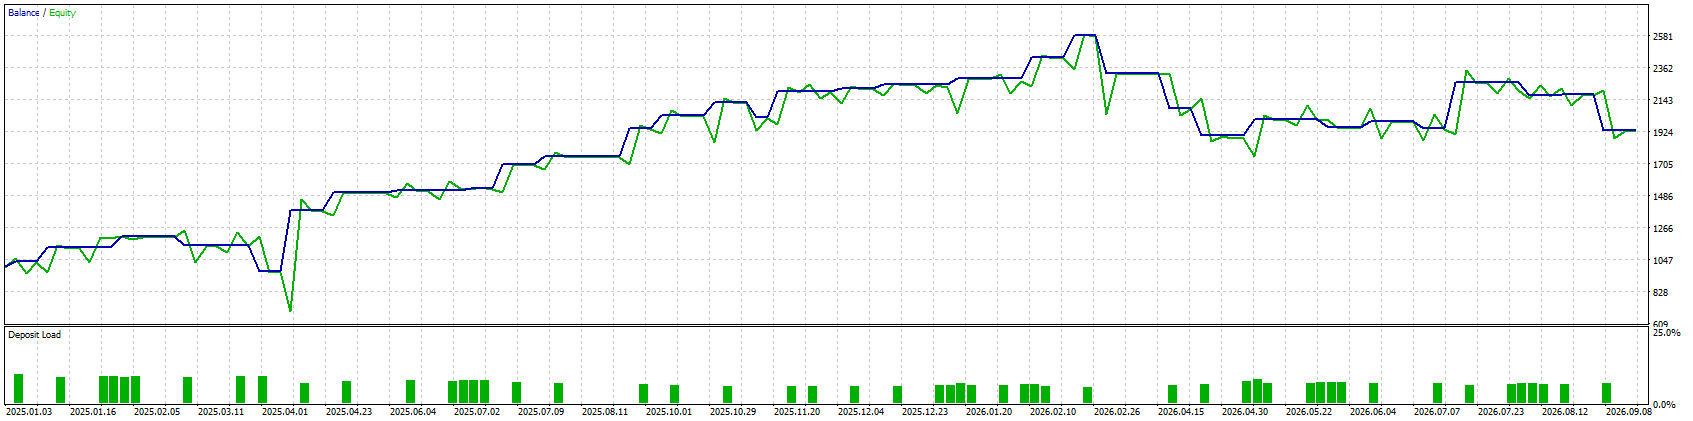
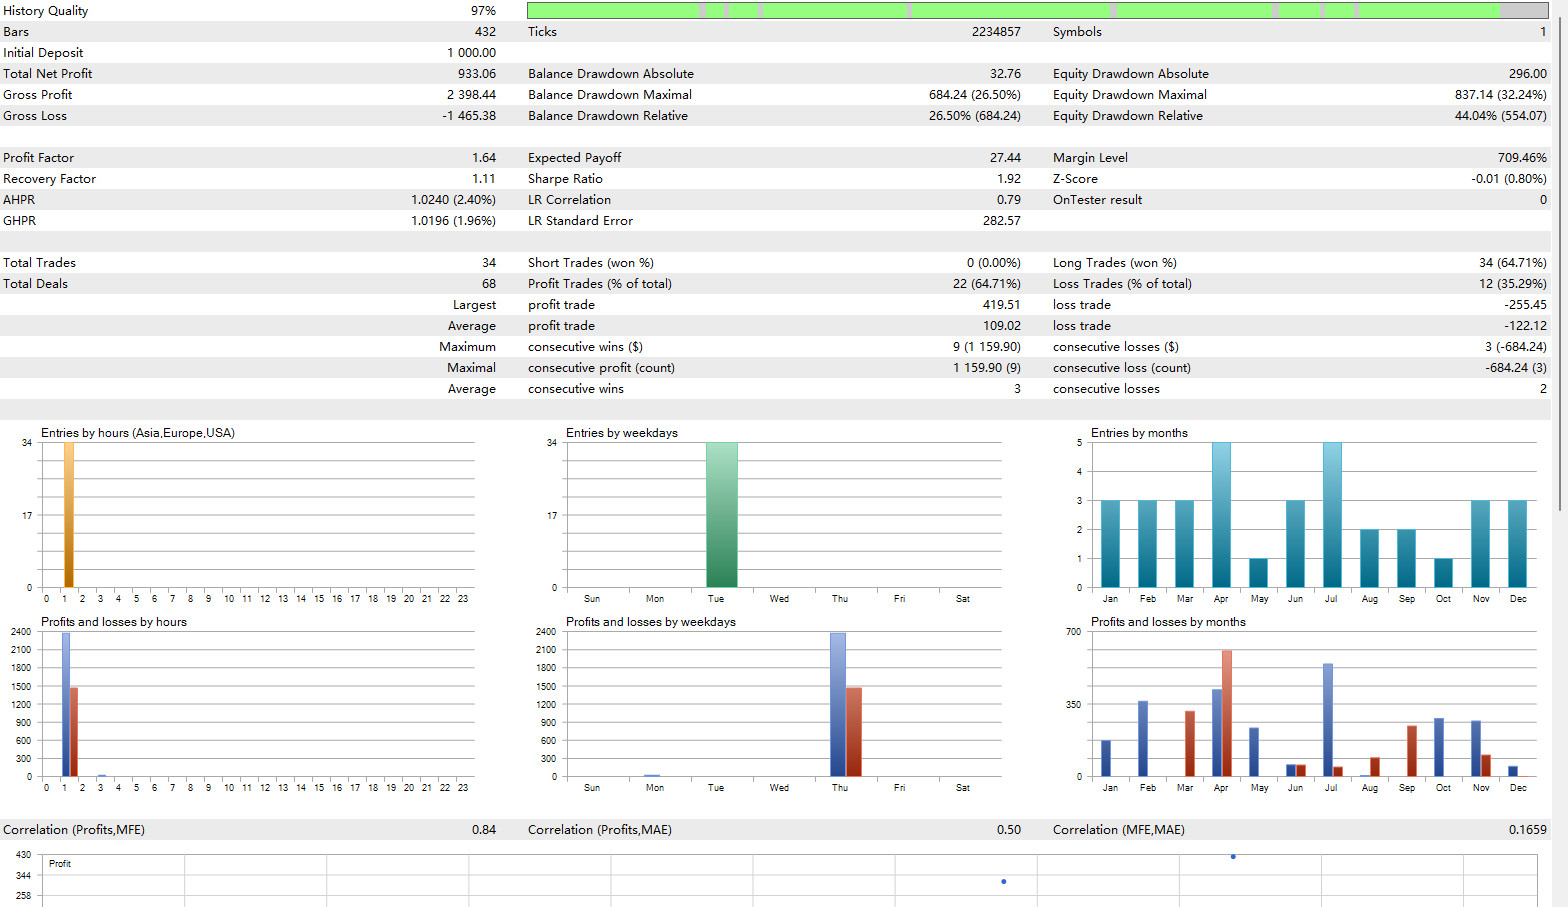
Risk control is structural rather than reactive. Only one position is open at a time, the trade is long only, and the holding period is capped at under two days because the position is closed when Wednesday closes, so nothing is ever carried over a weekend. The stop loss is a percentage of the entry price, 10% in the example, and is attached to the position at entry while respecting the symbol minimum stop distance. The strategy does not use a grid or martingale, so position size never escalates after a loss. In the daily timeframe backtest the balance drawdown was 684.24, or 26.50%, with equity drawdown relative at 44.04%, and the largest consecutive loss run was 3 trades. Live results since late May last year reported a profit factor of 2.59 with a peak return of 170% and recent return of 160%, with the return-to-drawdown ratio beating both the FTSE 100 and the S&P 500. Because drawdowns of this size are normal for the approach, the minimum tested balance is 1,000 and appropriate account sizing matters.
FTSE100 D1, SP500 D1
!!! READ BEFORE USE !!!
This EA is for educational and expert use only. Test on a DEMO account for at least 30 days before going live. By clicking "OK", you accept all market risks.